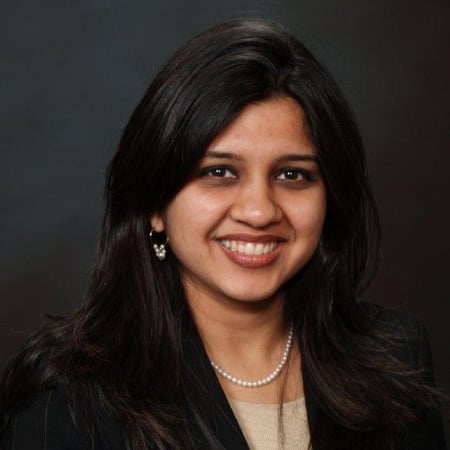
Mamta Shah
Trust Specialist


Complex wealth rarely fits into one category.
For some clients, complexity comes from real estate — uneven cash flow, leverage decisions, liquidity needs, taxes, and concentrated exposure. For others, it comes from a demanding medical career — delayed earnings, student debt, employer benefits, income protection, practice ownership, and compressed wealth-building years. For business owners, complexity often shows up through retirement plans, executive benefits, succession planning, key-person retention, and the overlap between business and personal wealth.
As a CFA® charterholder, I bring an analytical, investment-informed approach to helping clients coordinate these decisions into a clear plan. My work focuses on helping real estate professionals, physicians, and business owners evaluate the moving parts of their financial lives — investments, liquidity, retirement planning, workplace benefits, risk management, tax-sensitive strategies, and long-term goals.
The goal is simple: help you make better-coordinated financial decisions with the full picture in view.
What Sets My Approach Apart
Successful real estate investors often build substantial wealth in investment properties while keeping much of that wealth tied up in illiquid property equity. The result can be a strong balance sheet—but limited flexibility when an acquisition, renovation, refinance or unexpected expense requires capital.
I work with real estate investors and rental-property owners to organize the financial system surrounding their portfolios. This includes reviewing real estate equity, debt, cash flow, reserves, investment assets, borrowing capacity and long-term planning priorities in one coordinated framework.
The objective is not to promote more borrowing, more transactions or less real estate. It is to help you understand what you own, what you owe, what liquidity may be available and how each part of your balance sheet can support your next decision.
Property Rich, Cash Poor: When Real Estate Equity Is Not Liquidity
A real estate investor can have significant net worth and still lack ready access to capital. Property equity may look strong on a personal balance sheet, but equity alone cannot immediately fund a roof replacement, renovation overrun, earnest-money deposit or time-sensitive acquisition.
That is the difference between paper wealth and usable liquidity.
This issue commonly appears when:
The important question is not simply, "How much real estate equity do I have?"
It is: "How much usable liquidity do I have after accounting for reserves, debt service, collateral requirements and risk?"
A Coordinated Wealth Strategy for Real Estate Investors
Real estate and a diversified investment portfolio do not have to compete with each other. They can perform different jobs within the same wealth strategy.
Real estate may serve as a:
An investment portfolio may support:
The goal is not to choose between real estate and portfolio investing. The goal is to determine what job each asset should perform—and whether those assets work together.
What Real Estate Investor Wealth Planning Can Include:
Consolidating Your Real Estate Portfolio
Effective real estate portfolio planning begins with accurate, current information for each property:
A consolidated view creates the foundation for evaluating acquisitions, refinancing, renovations, liquidity needs and long-term portfolio decisions.
Translating Property Equity Into Practical Options
Not all real estate equity is equally usable. Some equity may support financial flexibility, while some may be better left untouched.
A real estate equity review may help identify capital that could potentially:
The objective is not to extract the maximum amount of equity. It is to determine whether using equity could strengthen the broader financial system without making a property unnecessarily fragile.
Reviewing Real Estate Debt and Cash Flow
Debt decisions should be evaluated through property-level mathematics—not blanket opinions about leverage.
A disciplined debt review considers:
Debt is not automatically beneficial or harmful. The important question is whether the property can support the obligation under conservative assumptions.
Evaluating Paid-Off and Low-Leverage Properties
Owning investment property free and clear may support simplicity, lower fixed obligations, conservative cash flow and reduced lender exposure.
However, a paid-off or low-leverage property may also hold capital that could potentially support:
The relevant question is not whether a property "should" have debt. It is whether its current capital structure fits the investor's cash-flow needs, risk tolerance, time horizon and objectives.
Pressure-Testing an Investment-Property Refinance
A refinance should be treated as a system decision—not merely a way to create cash.
Before refinancing an investment property, evaluate:
A responsible refinance should have a defined purpose. Creating liquidity without a reserve plan, deployment policy or cash-flow benefit can introduce unnecessary risk.
Building a Real Estate Investor Liquidity Strategy
Available capital is not automatically deployable capital. Real estate investors can benefit from separating liquidity into three distinct categories:
Property and Household Reserves
Capital intended to cover vacancies, repairs, taxes, insurance, debt service, market stress and personal liquidity needs.
Active Deal Capital
Funds assigned to current acquisitions, renovations, closing costs or defined bridge needs.
Opportunity and Contingency Capacity
Capital intentionally preserved for future investments, delays or unexpected circumstances.
Separating these liquidity buckets before the next transaction can help prevent reserve capital from being treated as deal capital.
Evaluating Portfolio-Based Lending
For qualified investors, borrowing against eligible investment assets may provide timing flexibility without requiring an immediate property refinance or sale of securities.
Potential uses may include:
Portfolio-based lending involves material risks and is not appropriate for every investor. A review should consider:
A credit line should be treated as debt—not as cash or free capital.
Creating a Disciplined Real Estate Deal Box
More properties do not automatically create a stronger real estate business. A defined deal box can help investors evaluate acquisitions consistently.
A deal box may include:
A documented deal box helps reduce emotional decisions and ensures that new opportunities are measured against established investment criteria.
Coordinating Your Real Estate Professional Team
Real estate investment decisions frequently involve several specialized professionals. Depending on the decision, the team may include:
Each professional remains responsible for guidance within their area. The planning process helps organize the facts so the team can work from a more consistent view of the investor's properties, debt, liquidity and objectives.
The Real Estate Wealth Dashboard
The Real Estate Wealth Dashboard is an organizing framework for investors who want their property portfolio and investment portfolio to work from the same set of facts.
It can help organize:
The Dashboard is not intended to replace your CPA, attorney, lender, insurance professional, property manager or other advisors. It is designed to support a more coordinated planning conversation.
How the Real Estate Wealth Dashboard Process Works:
Step 1: Organize
Bring property values, debt, cash flow, reserves, liquidity, investment assets and planning priorities into one working view.
Step 2: Identify Gaps
Highlight stale values, missing documents, upcoming capital needs, unclear assumptions and risks that require professional review.
Step 3: Prioritize
Determine which issue should be addressed first—reserves, refinancing, debt reduction, acquisition capital, investment portfolio structure, insurance or tax and legal coordination.
Step 4: Evaluate
Compare potential strategies against cash flow, borrowing costs, collateral requirements, reserves, risk tolerance and time horizon.
Step 5: Coordinate
Engage the appropriate professionals when tax, legal, lending, insurance or transaction-specific guidance is needed.
Step 6: Review
Update the Dashboard as property values, loans, rents, projects, investments and planning priorities change.
Decisions This Real Estate Planning Framework Can Support
This process may be useful if you are preparing to:
Who This Is For:
This framework is designed for real estate investors and property owners who:
Frequently Asked Questions
What is wealth planning for real estate investors?
Wealth planning for real estate investors coordinates investment properties with debt, cash flow, liquidity, reserves, investment assets, retirement planning and long-term objectives. The goal is to evaluate the investor's complete financial system rather than treating each property or account as an isolated decision.
What does "property rich, cash poor" mean?
"Property rich, cash poor" describes an investor who has substantial real estate equity but limited immediately available liquidity. Although the investor may have significant net worth, much of it may be tied up in properties and unavailable for acquisitions, renovations, reserves or unexpected expenses.
How can a real estate investor improve liquidity?
Potential approaches may include strengthening cash reserves, organizing property cash flow, reviewing debt, evaluating a refinance, maintaining investment assets outside real estate or considering an appropriate credit facility. Each strategy has costs and risks and should be evaluated based on individual circumstances.
Should real estate investors diversify beyond property?
Diversification may help reduce dependence on a single asset class, market or income source, but it does not guarantee a profit or protect against loss. The appropriate balance depends on liquidity needs, investment objectives, risk tolerance, time horizon, tax considerations and the role real estate plays within the investor's plan.
Is a paid-off rental property always better?
Not necessarily. A debt-free property may support simplicity, lower fixed obligations and conservative cash flow. It may also leave substantial capital tied up in an illiquid asset. The appropriate structure depends on the property's economics, the investor's reserves, risk tolerance and broader objectives.
What should be reviewed before refinancing an investment property?
Investors should consider property value, loan-to-value ratio, transaction costs, interest rate, annual debt service, post-refinance cash flow, reserve coverage, use of proceeds, repayment expectations, tax implications and the effect on the broader balance sheet.
What is a Real Estate Wealth Dashboard?
A Real Estate Wealth Dashboard is an organizing framework that consolidates property values, debt, cash flow, reserves, investment assets, liquidity sources, planning objectives and professional-team responsibilities into one structured view.
What documents are helpful for a Real Estate Wealth Dashboard conversation?
Useful documents may include property lists, valuation estimates, mortgage statements, rent and expense reports, insurance summaries, cash and investment statements, retirement-account statements, existing credit-line information and contact details for key professional advisors.
A physician's financial life is different from most professionals.
The career path often starts with years of training, delayed earnings, significant student debt, and limited time. Then income rises quickly, and the financial decisions become more complex: how much to save, how to invest, whether to pay down debt faster, how to evaluate employer benefits, how to protect income, when to buy into a practice, and how to plan for long-term wealth.
I help physicians and medical professionals coordinate these decisions into a clear plan. My focus is especially well-suited for physician practice owners, physician partners, high-income specialists, and established medical professionals who need planning that connects investments, benefits, taxes, risk management, practice ownership, and long-term family goals.
For Physicians Building Wealth After Training
Physicians often begin serious wealth-building later than peers in other fields. That can create a compressed planning timeline where savings rate, investment strategy, tax coordination, and retirement planning matter early.
Common Planning Issues:
For Established Physicians and Specialists
As income grows, decisions can become more technical. Higher compensation may create opportunities, but it can also increase tax exposure, investment complexity, insurance needs, and planning tradeoffs.
Common Planning Issues:
For Physician Practice Owners and Partners
Practice ownership adds another layer of complexity. Your financial life may include both personal wealth and business value, and decisions inside the practice can affect your household plan.
Common Planning Issues:
Core Planning Pillars
A thoughtful workplace wealth strategy can help business owners compete for talent, retain key employees, and reward the people who help drive the business forward.
For many companies, the right question is not simply, "Do we have a retirement plan?" The better question is, "Is our benefits strategy helping us achieve the goals of the business?"
That may include attracting stronger candidates, improving retention, rewarding leadership, creating owner and executive planning opportunities, and helping employees make more confident financial decisions.
Core Areas of Workplace Wealth Strategy
1. Retirement Plan StrategyYour company's retirement plan should be evaluated in the context of business goals, employee needs, owner objectives, and plan design opportunities.
This is especially important when business owners are considering whether their current plan is enough — or whether additional strategies may better align with their goals.
Areas of Focus:
2. Multiple Plan Evaluation
As businesses grow, leadership teams often need to evaluate more than one benefits strategy at a time.
A 401(k) plan may be the foundation, but it may not be the full answer. Depending on the business, ownership structure, employee demographics, cash flow, and retention goals, additional plan design conversations may be appropriate.
Areas of Focus:
3. Executive Benefits
For owners, executives, and key people, standard employee benefits may not fully address retention, retirement savings, or leadership continuity goals.
Executive benefits can be part of a broader conversation about how the business rewards leadership, retains important people, and aligns compensation with long-term priorities.
Areas of Focus:
4. Owner & Executive Planning Opportunities
Business owners and executives often have financial planning needs that go beyond the company retirement plan.
The right workplace wealth strategy should consider both sides of the equation: what the company is trying to accomplish and what the owners and executives are trying to accomplish personally.
Areas of Focus:
Additional Leadership & Fiduciary Considerations
| Day of the Week | Hours |
|---|---|
| Monday | 9:00 AM - 5:00 PM |
| Tuesday | 9:00 AM - 5:00 PM |
| Wednesday | 9:00 AM - 5:00 PM |
| Thursday | 9:00 AM - 5:00 PM |
| Friday | 9:00 AM - 5:00 PM |
| Saturday | Closed |
| Sunday | Closed |
Mamta Shah
Kimberly Emerson
Joshua Gilbert