
Phone:
(206) 344-2410(206) 344-2410

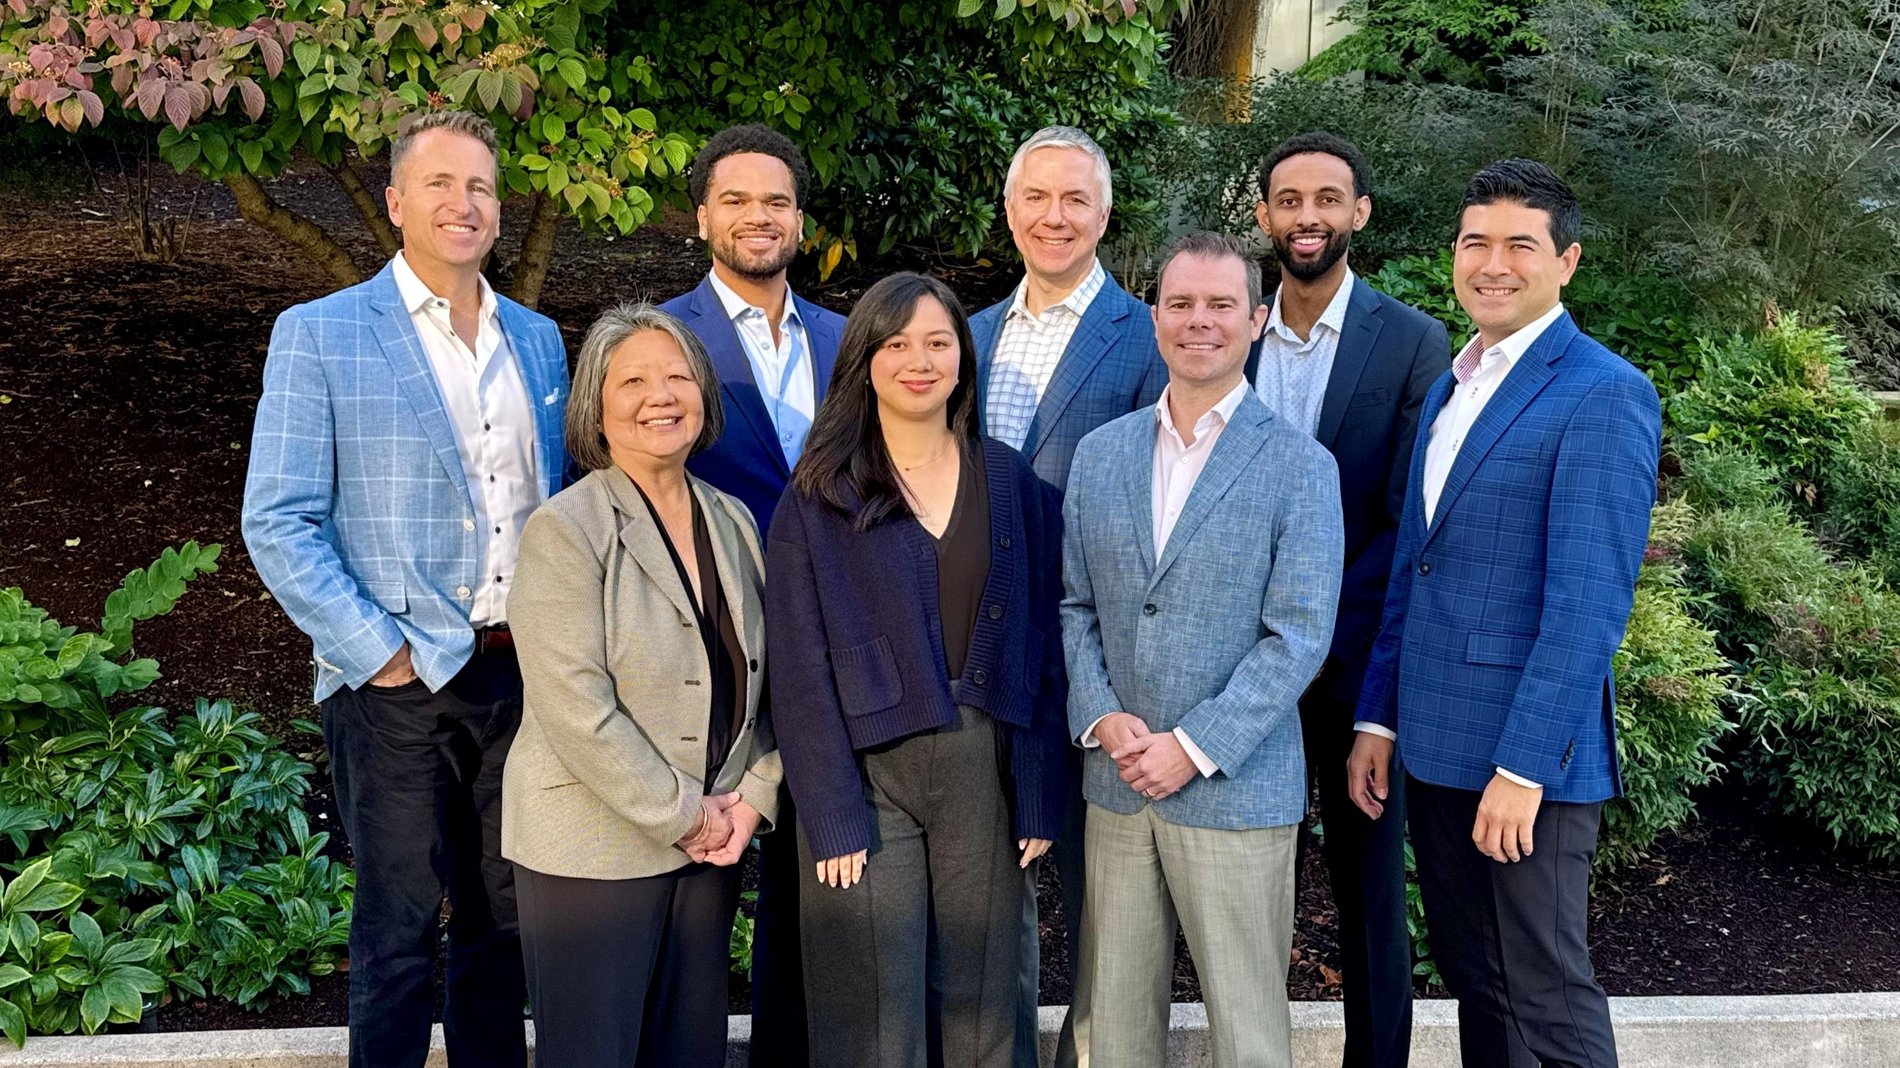
Wealth With a Purpose
Vasara is inspired by the Sanskrit word for day: the unit of a working life. Our clients have spent their days building careers, companies, and first-generation wealth. We help plan for the days ahead, so what they have can further serve the life, people, and purposes that matter most to them.
Our clients are founders, senior technology executives, entrepreneurs, and other high-achieving leaders whose financial lives tend to move faster — and become more complex — than a traditional wealth plan anticipates. Concentrated equity. Executive compensation. Liquidity events. Private investments. Tax exposure. Family wealth. At Vasara Wealth Management Group, we provide the sophistication to connect those pieces — and the perspective to know which ones matter most.
Four Disciplines. One Wealth Strategy.
Significant wealth rarely presents a single challenge. It creates interconnected decisions across investments, private markets, liquidity, lending, executive compensation, taxes, and family wealth.
Our practice brings together four core areas of excellence — comprehensive wealth and investment management, alternative investments, lending, and Executive Financial Services — so those decisions can be considered as part of one strategy. We bring specialized knowledge to the different dimensions of a client's financial life while keeping the focus on the whole picture.
Executive Compensation, Engineered with Precision.
Fewer than 1% of Morgan Stanley teams have the firm's HUB designation. We are one of them. That means we not only support executives with complex equity compensation and 10b5-1 planning requirements — we also work with public-company issuers to help structure and administer executive trading programs and support their operational execution. That depth matters. Because whether we are advising an individual executive or working with an issuer's stock plan team and general counsel, the mechanics of managing RSUs, options, restricted stock, concentrated positions, and trading plans subject to Section 16 reporting and other restrictions can have significant implications across liquidity, tax exposure, concentration risk, and long-term wealth strategy.
Intelligence Beyond Public Markets
We lean deeply into Morgan Stanley's robust private-market and alternative investment capabilities, including private lending, real estate, evergreen structures, and opportunities that can look more like venture or direct investing than traditional wealth management. Our goal is not complexity for complexity's sake. It's to give sophisticated investors more sophisticated choices — and the judgment to determine which choices are actually appropriate.
Wealth Gets More Complicated After You Make It
For first-generation wealth creators, building substantial wealth is one challenge. Deciding what happens to it next is another. We help clients think through the financial and human complexities that come with significant family wealth: estate planning, governance, and next-generation education to help prepare children to inherit wealth they did not build themselves. Ultimately, these are conversations about building a multigenerational legacy of excellence.
Your Thinking Partner
Our job isn't to tell you what to do. It's to help you ask better questions, illuminate blind spots, and execute the decisions you don't have time to implement yourself. For a second opinion about your current investments, or to talk about your goals, please call us at (206) 343-2762.
For senior executives and Section 16 insiders, equity compensation can represent the majority of their net worth — and come with a regulatory framework that leaves little room for improvisation. At Vasara Wealth Management Group, we specialize in helping executives navigate that complexity. As one of Morgan Stanley's specialized HUB Teams, a designation held by fewer than 1% of the firm's teams, we have been specifically vetted to support executives with sophisticated equity compensation and trading requirements.
Built for the Realities of Executive Compensation
Executive compensation rarely arrives in one form. RSUs, stock options, restricted stock, performance awards, ESPPs, and other forms of equity can create different tax, liquidity, and risk considerations. We help executives understand how those pieces interact and develop a disciplined path from concentrated equity to diversified wealth. That can include:
The Advantage Is Between the Lines
Many advisors work with executives who have 10b5-1 plans. Very few work directly inside the process, alongside the issuer, its counsel, and its stock plan team. That distinction gives us a different perspective on what can go right, what can go wrong, and what needs to be considered before a plan ever reaches execution. We understand the operational constraints, the governance requirements, and the financial decisions surrounding the plan — not just the investment strategy after the shares are sold. For executives whose compensation, reputation, and financial future are closely tied to a public company, that level of precision is critical.
Built for What Comes Next
Executive compensation is only one component. As equity becomes liquidity, the questions evolve: How much should remain invested? How should proceeds be allocated? What does the tax picture look like? How should private investments, real estate, philanthropy, estate planning, and family wealth fit into the equation? Our role is to stay ahead of those transitions and help you turn the value you've created into lasting wealth.
When Your Compensation Becomes Your Wealth
After years of building a career in technology, a senior executive had accumulated substantial RSUs, Incentive Stock Options (ISOs), and other equity awards — but little time to think about what came next. Between vesting schedules, a concentrated position, trading restrictions, and the potential Alternative Minimum Tax implications associated with exercising ISOs, the equity that created the wealth was becoming one of its biggest planning challenges.
Our team helped bring the pieces together, from 10b5-1 planning, option exercise strategy, and tax considerations to liquidity and diversification. As shares were monetized, we helped develop a plan for redeploying capital into a globally diversified portfolio spanning both public and private markets, including alternative investments designed to provide access to additional sources of return, diversification, and income for eligible clients.
The objective was straightforward: help turn a complex compensation package into a deliberate, diversified wealth strategy — while drawing on Morgan Stanley's broad investment platform and specialized capabilities to identify appropriate opportunities across both traditional and alternative markets.
Takeaway: For many of our clients with demanding careers, time is one of their most precious assets. Our goal is to help you spend it where it creates the most value.
-
When the Cap Table Becomes the Balance Sheet
After a liquidity event, the balance sheet can suddenly look very different. For many founders and executives, that change brings an unexpected question: Is this really enough to support me and my family for the rest of our lives?
Vasara helps clients answer that question by defining what we call a "lifetime spending endowment" — the pool of capital required to support a client's desired lifestyle, spending needs, and long-term obligations after taxes. From there, the team can work backward to design an investment strategy intended to sustain those needs over time.
That portfolio is then stress-tested from multiple angles. Monte Carlo analysis can help quantify the probability of achieving the client's goals across thousands of potential outcomes, while Morgan Stanley's Portfolio Risk Platform can evaluate portfolio risk against historical market events and other economic scenarios.
Once clients have greater confidence that their lifetime needs are accounted for, the conversation can expand. Capital that is not required to support the core lifestyle can be considered in the context of philanthropy, wealth transfer, entrepreneurial opportunities, or further wealth creation. The objective is not simply to build a portfolio. It is to create a durable financial foundation that gives clients greater freedom to focus on what matters most.
Takeaway: When clients can quantify what they truly need and build a portfolio designed to support it, wealth can become less about uncertainty and more about creating freedom and optionality.
-
Building Wealth Is Only the First Chapter
Significant wealth can create complexity, whether it was built in one generation or inherited from another. For families receiving substantial inherited wealth, that can mean deciphering trust structures, understanding trustee responsibilities and reporting requirements, and determining whether existing arrangements remain appropriate.
Vasara helps families make that complexity more understandable. The team may create trust maps that clarify how assets, entities, beneficiaries, and trustees fit together; help evaluate and select corporate trustees; and coordinate with legal and tax professionals around the broader estate structure.
Just as important is preparing the generation that will ultimately inherit responsibility for the wealth. Vasara works across generations to build financial fluency over time, from fundamentals such as budgeting, saving, and investing to more sophisticated concepts involving trusts, portfolio management, philanthropy, and family governance.
For first-generation wealth creators, the challenge often begins one step earlier: establishing the structures, decision-making framework, and family education that future generations will inherit. Drawing on Morgan Stanley's broader family office resources, Vasara helps families think beyond transferring assets to transferring the knowledge and judgment required to steward them.
Takeaway: Successful wealth transfer is about more than passing assets from one generation to the next. It also requires preparing people, structures, and decision-making frameworks to sustain that wealth over time.
-
Preparing a Company and Its Executives for an IPO
Going public changes far more than a company's capital structure. It introduces new responsibilities for executives, directors, insiders, and the stock plan teams responsible for supporting them.
Vasara works with companies preparing for an IPO to help build the infrastructure around those responsibilities. That can include educating issuers on insider trading policies, developing initial 10b5-1 plan templates and adoption processes, establishing procedures for Rule 144 open-market transactions, and preparing executives for post-IPO lockups, equity-award decisions, tax considerations, and market optics.
By the time the company goes public, the goal is to have a comprehensive Executive Concierge Program in place for Section 16 affiliates and other insiders. That includes education around SEC reporting requirements, the role of 10b5-1 plans in providing an affirmative defense against insider trading allegations when properly established and followed, internal approval processes, trade reporting, and ongoing support around executive equity compensation.
For stock plan administrators, the value is practical as well as strategic: a specialized team that can help reduce the administrative burden while providing senior executives with a higher level of education, coordination, and support as they transition into life as insiders of a public company.
Takeaway: The right infrastructure before an IPO can reduce the burden on internal teams, prepare executives for the responsibilities of public-company ownership, and create a more coordinated experience once the company enters the public markets.
What is Vasara Wealth Management Group?
Vasara Wealth Management Group is a Seattle-based team at Morgan Stanley that works with senior technology executives, founders, entrepreneurs, and first-generation wealth creators across the country whose wealth is closely tied to equity compensation, private companies, or liquidity events. The team combines wealth and investment management, alternative investments, lending, and Executive Financial Services in a single coordinated strategy. Vasara is one of Morgan Stanley's designated HUB Teams, a designation held by fewer than 1% of Morgan Stanley teams, which work with public companies and companies preparing to go public on executive trading programs, including 10b5-1 plans, as well as with the executives those programs serve.
Who does Vasara Wealth Management Group work with?
Based in Seattle, Vasara Wealth Management Group works primarily with senior technology executives, founders, entrepreneurs, and first-generation wealth creators across the country. Many clients have significant equity compensation, concentrated positions, liquidity events, private investments, or other complexities that require more than traditional portfolio management.
What makes Vasara different from other wealth management teams?
Vasara combines deep experience in executive compensation, lending solutions, alternative investments, and family wealth with the broader resources of Morgan Stanley. The team's clients tend to be financially sophisticated and capable of managing many aspects of their wealth themselves. Vasara's role is to bring deeper insight, ask better questions, identify blind spots, and coordinate financial decisions that are difficult to manage independently.
What is a 10b5-1 trading plan?
A Rule 10b5-1 trading plan is a predetermined program for buying or selling company securities that can provide an affirmative defense against insider trading liability when properly established and operated. These plans are particularly relevant for executives and other insiders who may regularly possess material nonpublic information and therefore face restrictions on when they can trade company stock.
Who needs a 10b5-1 plan?
10b5-1 plans can be particularly useful for executives, directors, officers, and other insiders of publicly traded companies who are subject to insider trading restrictions or Section 16 reporting requirements. The appropriate structure depends on the individual's role, equity position, trading restrictions, liquidity needs, and broader financial strategy.
Why does 10b5-1 planning require specialized expertise?
A 10b5-1 plan is not simply an instruction to sell a certain number of shares. Its structure can affect diversification, liquidity, taxes, concentration risk, and the timing of equity monetization. The plan also needs to operate within applicable corporate policies, trading restrictions, and legal and compliance requirements. Vasara brings specialized experience to both the strategy and operational execution of these plans.
What is a Morgan Stanley HUB Team?
A Morgan Stanley HUB Team is a specialized team that has been designated to support executives and other clients with complex equity compensation and trading requirements. Vasara is one of Morgan Stanley's HUB Teams, a designation held by fewer than 1% of Morgan Stanley teams.
How is Vasara different from an advisor who simply recommends a 10b5-1 plan?
Vasara advises executives on how to structure 10b5-1 plans within the broader context of their financial lives, including tax considerations, option exercises, liquidity needs, risk management, and other planning priorities. That advisory depth is materially different from a do-it-yourself approach. Executives who attempt this independently, whether exclusively on their own or with the help of online tools and AI, often don't know the critical questions to ask, and that is where a significant oversight or misstep can occur.
For public companies, Vasara builds customized Executive Concierge Programs and serves as a designated broker for each issuer onboarded. Working closely with the issuer's stock plan team and general counsel, the team executes open-market trades and 10b5-1 plans for Section 16 affiliates and other insiders, including board members, C-suite executives, and senior company leaders. This highly customized service model is a distinctive part of its offering.
The team also works closely with Morgan Stanley at Work, coordinating with colleagues at E*TRADE and Shareworks who help administer company-wide equity compensation plans. Together, these capabilities allow the team to support both the executives participating in those plans and the public companies that sponsor them.
What types of equity compensation does Vasara work with?
Vasara works with executives navigating complex equity compensation, including Incentive Stock Options (ISOs), Nonqualified Stock Options (NQSOs), Employee Stock Purchase Plans (ESPPs), Restricted Stock Units (RSUs), Performance Stock Units (PSUs), Qualified Small Business Stock (QSBS), and other forms of company equity.
Through the team's comprehensive Equity Award Analysis, Vasara helps clients aggregate and quantify their equity holdings, giving executives a clearer view of what they own, when awards vest or become exercisable, and the potential tax and liquidity implications. That analysis can then inform a coordinated strategy for managing concentrated equity exposure within the context of the client's broader wealth plan.
How should I manage a concentrated position in my company stock?
There is no universal answer, and in many cases, the right strategy involves a combination of approaches. Vasara frames these decisions using a structured process called H.O.P.E.S.: Hold; Options, including hedging and monetization strategies; Philanthropy and charitable giving; tax-deferred Exchanges or Extension strategies; and Sell.
The answer is often not either/or, but both/and. Depending on the executive's circumstances, multiple strategies may work together to address concentration risk, taxes, liquidity needs, diversification, and long-term goals. Vasara brings intellectual rigor to these decisions by combining quantitative analysis with qualitative, vision-based planning to help clients determine which approaches, and which combination of approaches, best support their broader wealth strategy.
How does Vasara integrate equity compensation with overall wealth planning?
The team looks at equity compensation as one component of the broader balance sheet. RSUs, options, restricted stock, and other equity can affect liquidity, taxes, portfolio construction, estate planning, and risk. In practical terms, those considerations help shape savings targets, diversification goals, and risk management objectives that feed directly into Monte Carlo financial planning analysis.
Vasara uses that analysis to help quantify the probability of achieving the goals each client defines — whether that means retirement, wealth transfer, philanthropy, or other long-term priorities. The objective is to coordinate equity compensation with the broader wealth strategy in ways that can increase the probability of successfully achieving those vision-driven goals.
Does Vasara offer access to alternative investments?
Vasara has deep experience accessing Morgan Stanley's alternative and private-market offerings. With three Alternative Investments Directors on the team, Vasara helps clients navigate the firm's extensive capabilities across private lending, real estate, evergreen structures, direct private placements, and co-investment opportunities for eligible clients.
That combination of specialized team expertise and Morgan Stanley's broader platform gives Vasara the infrastructure to source, evaluate, and incorporate alternative investments within a client's overall portfolio and wealth strategy.
Why do Vasara clients invest in alternatives?
Many Vasara clients are already sophisticated investors and are interested in opportunities beyond traditional public markets. Some may be seeking alpha by capturing the illiquidity premium. Others may be looking for meaningful diversification through investments with lower correlation to public markets, or for opportunities to enhance tax-advantaged income.
Often, the objective is not either/or, but a combination of these goals. Vasara helps clients evaluate how alternative investments fit within the broader portfolio and whether they can meaningfully improve return potential, diversification, income, and tax efficiency rather than simply adding complexity for its own sake.
What types of private investments does Vasara consider?
Depending on a client's objectives and suitability, Vasara can evaluate opportunities across private credit and lending, real estate, evergreen private-market structures, direct private placements, co-investment opportunities, and investments with characteristics closer to venture or direct investing.
Are alternative investments appropriate for every investor?
No. Private and alternative investments can involve significant risks, including illiquidity, valuation uncertainty, complexity, and potentially long investment horizons. Vasara evaluates these strategies within the context of a client's liquidity needs, risk profile, existing portfolio, and broader financial objectives.
How does Vasara decide whether an alternative investment belongs in a portfolio?
The starting point is the objective. The team considers what the client is trying to accomplish, including return and income objectives, risk management priorities, liquidity needs, tax considerations, and the role the investment is intended to play within the existing portfolio. The goal is to evaluate each opportunity in the context of the broader capital strategy and optimize for risk-adjusted return.
Access is not the same thing as allocation. Vasara focuses on whether an opportunity makes sense within the larger portfolio — and whether it helps advance the client's overall investment, income, liquidity, and risk management objectives.
Can Vasara help with lending and liquidity needs?
Yes. Vasara has deep experience helping clients evaluate lending as part of their broader wealth strategy, including securities-based lines of credit and jumbo mortgages. With Lending Specialist expertise on the team, Vasara can help clients consider when borrowing may make sense alongside their investments, liquidity needs, tax considerations, and other financial priorities.
Does Vasara work with publicly traded companies as well as individual executives?
Through its Executive Financial Services capabilities, Vasara works with publicly traded issuers and companies preparing to go public, to develop formal Executive Concierge Programs for board members, C-suite executives, and other senior leaders.
These programs are designed to meaningfully reduce the administrative burden on stock plan teams while helping companies establish the infrastructure needed to support insiders. Vasara can assist with insider trading policies, initial 10b5-1 plan templates, documented adoption processes for open-market trades and 10b5-1 plans, trade reporting, and Form 144 filings for Section 16 affiliates and other insiders.
The team also serves as a point of coordination across the broader Morgan Stanley platform, connecting issuers and executives with capabilities such as corporate cash management, deferred compensation, retirement plans, investment banking, and broader wealth management. With an Executive Financial Services Director on the team, Vasara brings specialized experience to both the corporate and personal financial complexities surrounding senior executives.
What should I do with my money after selling a business?
A business sale can fundamentally change the structure of a client's balance sheet. Years of concentrated operating risk may suddenly become cash and investable assets, often alongside a significant tax liability and new liquidity needs. Vasara helps clients evaluate the balance sheet after the transaction, including liquidity reserves, tax obligations, public and private investments, real estate, diversification, and long-term family capital.
How does wealth planning change after a liquidity event?
Before an exit, the central question is often, "Do I have enough?" After a liquidity event, it becomes, "Now what?" That shift introduces a different set of planning challenges, from managing concentrated stock and determining how much capital to keep liquid or invest, to addressing legacy, estate, and wealth-transfer priorities.
These decisions require different planning disciplines and tools than those used during the wealth-creation phase. Vasara helps clients navigate that transition, moving from building wealth to designing how that wealth should be allocated, protected, transferred, and put to work over time.
How should I diversify after selling a company?
Diversification after a liquidity event should account for more than asset-class percentages. Vasara considers tax exposure, liquidity requirements, existing real estate and private investments, risk tolerance, family objectives, and the client's desired level of future investment activity. The goal is not simply to spread capital across more investments. It is to create a deliberate capital-allocation strategy.
Do entrepreneurs need a wealth manager if they have successfully managed their own money?
Many Vasara clients are highly capable investors and have managed their own finances successfully for years. The question is often one of focus and opportunity cost. For a founder or executive running a company, raising capital, managing a team, or spending time with family, managing every aspect of a complex balance sheet may not be the highest-value use of their time. Vasara serves as a thinking partner — bringing specialized expertise, perspective, and execution to the areas clients may prefer to delegate.
What is first-generation wealth?
First-generation wealth generally refers to substantial wealth created by an individual or couple rather than inherited from previous generations. Vasara works with many clients who have built significant wealth through technology careers, entrepreneurship, equity compensation, and business ownership.
Given the team's deep focus on the technology sector, many of these clients are also first-generation Americans or have built their careers and wealth after coming to the U.S. from abroad. That can add another layer of complexity to planning, particularly around family obligations, cross-border considerations, wealth transfer, and defining what newly created wealth should make possible for future generations.
Why is managing first-generation wealth different?
First-generation wealth creators often have significant financial sophistication but no inherited playbook for managing substantial family wealth. They may be navigating trusts, estate planning, philanthropy, family governance, private investments, and wealth transfer for the first time. Vasara helps clients build the framework that previous generations may have handed down to them.
What does a Family Wealth Director do?
A Family Wealth Director helps clients address the broader issues that accompany significant family wealth, including estate planning, family governance, intergenerational wealth transfer, and next-generation education. Vasara's Family Wealth Director capability becomes particularly relevant for clients who are thinking beyond their own financial lives and beginning to plan for children and future generations.
How do I prepare my children to inherit significant wealth?
There is no single answer. Preparation can involve education, family conversations, governance structures, trusts, staged access to assets, and a deliberate approach to when and how children become involved in family financial decisions. For first-generation wealth creators, these questions can be especially difficult because there is no family precedent to follow. Vasara helps clients think through both the financial structures and the conversations surrounding them.
Should I simply leave my children the money?
An inheritance strategy is about more than transferring assets efficiently. For families with significant wealth, the structure, timing, governance, and education surrounding a transfer can be just as important as the assets themselves. Vasara works with families to consider how wealth can support the next generation without creating unnecessary dependence, conflict, or lack of preparation.
When should I start talking to my children about family wealth?
There is no universal age or timeline. The right approach depends on the family, the children's maturity, the complexity of the assets, and the intended wealth-transfer strategy. But generally speaking, if a child is old enough to ask a question, they are old enough to receive an age-appropriate answer.
What matters is creating an ongoing dialogue rather than waiting until assets are already changing hands. Vasara helps families think through how to introduce the next generation to wealth gradually, intentionally, and in a way that evolves as their understanding and responsibilities grow.
How does Vasara approach tax management?
Tax considerations are integrated into broader wealth strategy rather than treated as an afterthought. For executives and founders, this can include evaluating the tax implications of equity sales, option exercises, liquidity events, capital gains, investment income, and wealth-transfer strategies. Vasara coordinates with a client's tax and legal professionals where appropriate to ensure investment decisions are considered within the broader tax picture.
How does Vasara think about liquidity?
Liquidity is a strategic component of wealth management. Clients may need capital for taxes, real estate, family expenses, philanthropy, future investments, or periods between liquidity events. Vasara evaluates liquidity needs alongside portfolio construction, private-market commitments, concentrated equity, and longer-term capital objectives.
How does Vasara integrate estate planning with investment management?
Estate planning and investment strategy can have significant overlap, particularly for first-generation wealth creators with concentrated equity, private investments, real estate, and substantial liquid assets. Vasara works alongside estate-planning professionals to help ensure investment decisions and estate structures are considered as part of a coordinated wealth strategy.
What does it mean to have Vasara as a "thinking partner"?
A thinking partner does more than implement instructions. Vasara helps clients identify the questions behind the decision, challenge assumptions, surface blind spots, and coordinate the moving pieces. For a technology executive considering a large equity sale, for example, the question may not be simply "Should I sell?" It may be "How much concentration am I comfortable retaining, what are the tax consequences, how should the sale be structured, and what should the capital do afterward?"
Does Vasara replace my CPA or attorney?
No. Wealth management often requires coordination among multiple professionals. Vasara works alongside a client's tax, legal, estate-planning, and other professional advisors where appropriate, helping ensure that investment and wealth-management decisions are considered within the larger financial architecture.
Rather than relying solely on in-house resources, Vasara takes an open-platform approach, working with specialized professionals who are well suited to the client's particular needs. While fully integrated firms may offer simplicity, this open architecture can provide greater flexibility to assemble the right guidance for complex tax, legal, estate, and wealth-planning issues.
What does a typical relationship with Vasara look like?
The relationship is built around the client's financial complexity and priorities rather than a standardized checklist. For an executive, that may mean coordinating equity compensation, 10b5-1 planning, tax-aware diversification, and liquidity. For an entrepreneur, it may center on a liquidity event and capital allocation. For a first-generation wealth creator, it may increasingly include estate planning, family governance, and next-generation preparation.
Why work with Vasara instead of managing everything myself?
Because capability and capacity are different things. Many clients could manage portions of their financial lives themselves. The question is whether doing so is the best use of their time, attention, and expertise, and whether they know all the questions they should be asking.
Information and technology, including AI, can make financial knowledge more accessible. But the quality of an answer often depends on the quality of the question, and complex decisions still require judgment, context, and validation grounded in experience. Vasara brings specialized knowledge, institutional resources, investment access, and ongoing perspective to the areas where complexity makes delegation valuable.
What resources does Vasara have access to through Morgan Stanley?
Vasara can draw on Morgan Stanley's broader investment and wealth-management platform, including alternative and private-market investments, lending, research, family office resources, and specialized capabilities for executives and other complex client situations.
But access alone is not the differentiator. In a firm with capabilities this extensive, relationships, experience, tenure, and the ability to navigate the organization matter. Vasara has built deep relationships across Morgan Stanley that can help connect clients quickly with specialized expertise when a situation demands it, often putting the team only a call or two away from leading professionals across the firm.
The value is not simply having a large platform available. It is knowing whom to call, how to engage the right resources, and how to bring that expertise to bear on a particular client need.
| Day of the Week | Hours |
|---|---|
| Monday | 8:00 AM - 5:00 PM |
| Tuesday | 8:00 AM - 5:00 PM |
| Wednesday | 8:00 AM - 5:00 PM |
| Thursday | 8:00 AM - 5:00 PM |
| Friday | 8:00 AM - 5:00 PM |
| Saturday | Closed |
| Sunday | Closed |
Rod S. Greenshields, CFA
Doug A. Webb, CFP®
Chris Rhea
Malcolm Prevo
Jo-Ann Loo
Matthew Samson
Sidney Menez
Katie Reed